
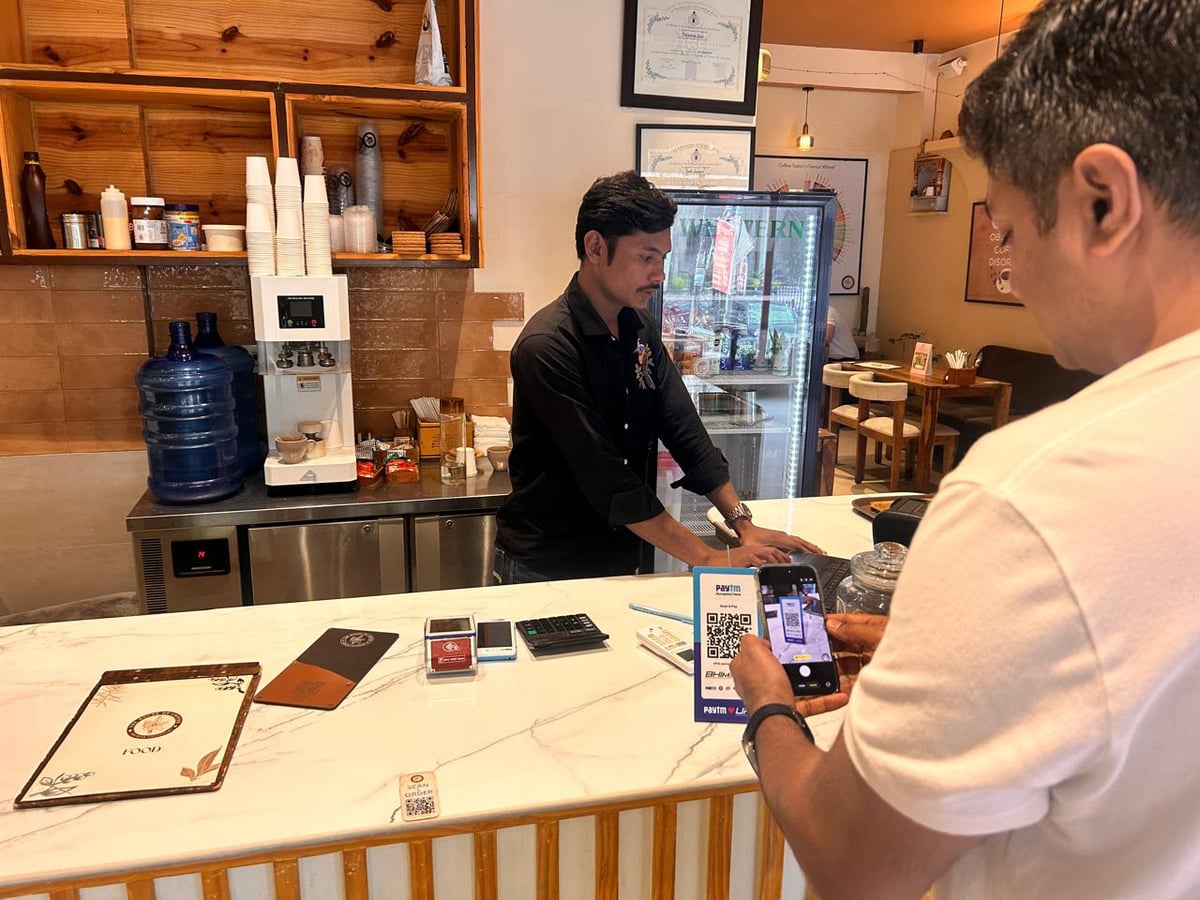
A severe wave of discontent has swept across the business community in Rajasthan as traders and commercial organizations voice vehement opposition against the proposed financial charges on Unified Payments Interface transactions. The controversy centers around the controversial Merchant Discount Rate and associated transaction fees, which traders argue will destabilize the financial footing of small retail establishments. Business associations across the state have convened urgent meetings to evaluate the profound economic repercussions of these processing costs on daily commercial operations.
The current impasse traces its origins to the evolving commercial models governing digital financial transactions in India. Over recent years, digital payments have transformed the retail landscape, offering unprecedented convenience to consumers and merchants alike. However, the underlying infrastructure supporting these instant transfers involves processing costs traditionally absorbed or disputed by financial intermediaries, payment aggregators, and merchants. The resurgence of discussions regarding transaction fees has triggered profound anxiety among commercial operators who previously relied on zero-fee structures to promote digital adoption.
Ground-level assessments reveal that small business owners, micro-retailers, and independent vendors bear the brunt of these financial policies. While large corporations and major retail chains possess the bargaining power and capital reserves to absorb minor transactional overheads, small-scale enterprises operate on extremely thin profit margins. The accumulation of processing fees on high-volume, low-value digital transactions significantly erodes the daily earnings of independent shopkeepers, making the acceptance of digital payments economically unviable for smaller establishments.
Prominent representatives of various trade organizations have articulated grave concerns regarding the ultimate distribution of these financial burdens. Stakeholders emphasize that any imposition of transactional costs on merchants will inevitably create a cascading economic effect, driving up prices of everyday commodities and directly impacting ordinary consumers. Several trade bodies have formally cautioned that if the financial liabilities associated with payment processing are not comprehensively resolved, small business owners will be compelled to discontinue UPI acceptance entirely.
Within the regional context of local markets, the threat of suspending digital payment options carries monumental implications for daily commerce. Consumers have grown accustomed to the seamless nature of cashless transactions, and any disruption in digital payment availability threatens to paralyze retail trade. Local shopkeepers and neighborhood vendors find themselves caught between the necessity of modernizing their payment systems and the prohibitive costs demanded by payment service providers.
As the agitation gains momentum, the trading community awaits formal intervention, constructive dialogue, and regulatory clarity from financial authorities and administrative bodies. Commercial associations have continuously stressed the urgent need for a balanced framework that safeguards the interests of grassroots merchants without stifling the nation's progress toward a cashless economy. Administrative oversight and policy adjustments remain imperative to prevent widespread service disruptions across the state's commercial hubs.
Looking ahead, the resolution of this contentious issue will heavily depend on collaborative discussions between digital payment aggregators, regulatory institutions, and trader representatives. The ongoing resistance serves as a critical reminder of the economic complexities underlying digital financial infrastructure. Stakeholders across the board maintain a watchful stance as negotiations continue to determine the future viability of fee-free digital transactions for small businesses.